Student Loan Refinance
I Saved Thousands Refinancing My Student Loans. You Could Too.
I didn't realize how much extra I was paying until I checked. My credit had improved since I first took out my loans, but I was still stuck paying the same old rate. That gap was quietly costing me thousands.
Your rate isn't getting better on its own
Interest on your student loans is accruing right now, locked in at whatever rate you qualified for years ago. If your credit score or income has improved since then, your loan doesn't know it and doesn't care. You keep paying the old rate until you do something about it.
This isn't the kind of debt problem that forces your hand. There's no warning sign, just a slow drain of money every month, for as long as the loan lasts. And with refinance rates now starting around 4% for well-qualified borrowers, that gap between what you're paying and what you could pay is only getting more expensive to ignore.
The Cost of Waiting is Thousands
Here's what the math actually looks like. Say you owe $25,000 at 6.5% over 15 years. You'll pay more than $14,000 in interest alone.
Refinance to 4.5% on the same term, and you save about $4,700. Keep your original rate but shorten to a 10 year term, and you save more than $5,100. Do both, and you save a combined $8,100.
That's real money, and it adds up daily. The longer you wait, the more of it you hand over instead of keeping. Comparing your refinance options only takes a couple minutes, so there's no real reason to put it off.
Compare student loan refinance rates in your state
Rates and lenders vary by where you live. Click your state to see the prequalified offers you could get — about two minutes, soft credit check only.
The Fix: Refinancing to a Lower Rate
Refinancing swaps your current loan for a new one from a private lender, based on your finances today instead of when you first borrowed. If your credit and income look better now, you could get a lower rate, a shorter term, a lower monthly payment, or one simple loan instead of several.
Most lenders charge no origination fees and no prepayment penalties. Checking your rate takes about two minutes and uses a soft credit pull, so you can see real numbers without hurting your score. (One exception: refinancing federal loans means giving up income-driven repayment and forgiveness programs, so weigh that first. If your loans are private, there's little downside.)
The Solution is Easier (and Faster) Than You Think
Comparing lenders one by one felt like a part-time job, so I used Credible instead. It's a marketplace that shows you prequalified rate offers from multiple lenders side by side, in about two minutes, with a soft credit check only.
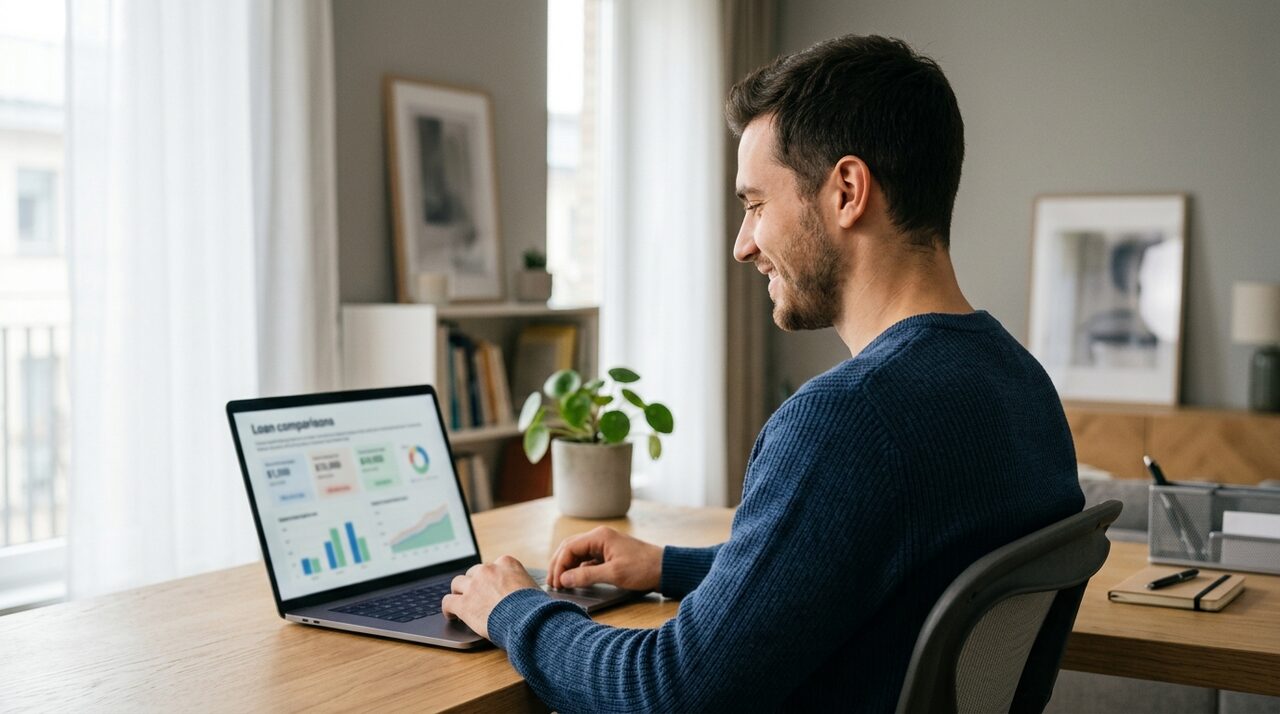
You answer a few quick questions about your loans and goals, compare real offers, and pick what fits. No obligation, no hard inquiry just to look.
Two minutes to check is a small trade against thousands of dollars in interest you're otherwise on track to pay.
It takes about two minutes, and there's no cost to look.
Sources: Money.com and Credible.com.